TAXATION
FOR DOCTORS
WHAT YOU’LL LEARN
PREMISE
WHY UNDERSTANDING TAXES MATTERS
THE REALITY
- Doctors are required to (1) register with the BIR, (2) issue invoices and (3) file taxes.
- These are legal responsibilities, not optional tasks.
- Tax compliance can ironically be good for your cash flow.
THE CHALLENGE
- Withholding taxes are reported to BIR and that’s one way our earnings can be tracked.
- Too many forms, rules, penalties plus no clear guidance.
- Different RDOs and personnel can have varying interpretation and application.
This discussion aims to help you understand taxes, maximize income,
avoid penalties and generally have some peace of mind.
FUNDAMENTALS
National Internal Revenue Code
All persons engaged in business or in the practice of their profession, including doctors, must issue registered receipts or invoices for each sale or transfer of merchandise or services.
Every person subject to any internal revenue tax, which includes doctors, must register with the appropriate Revenue District Office (RDO) and secure a Tax Identification Number (TIN).
BIR
REGISTRATION
Registration Requirements
TIN
Alternative: Birth Certificate
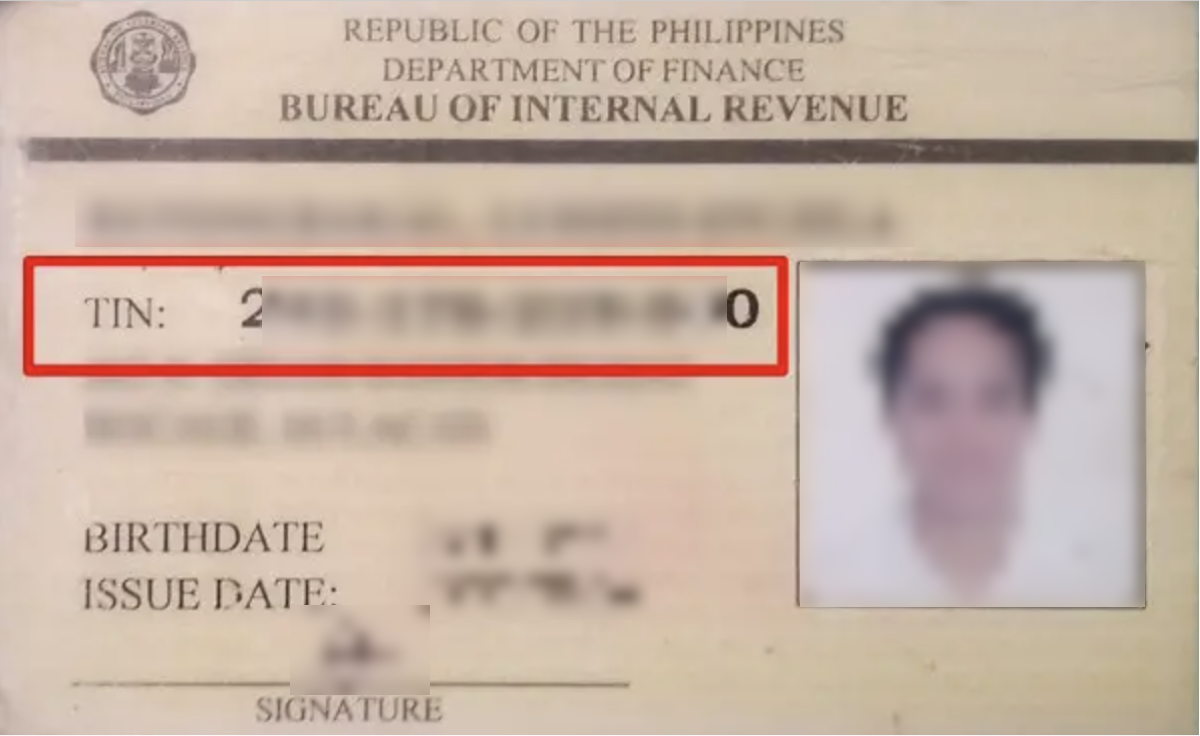
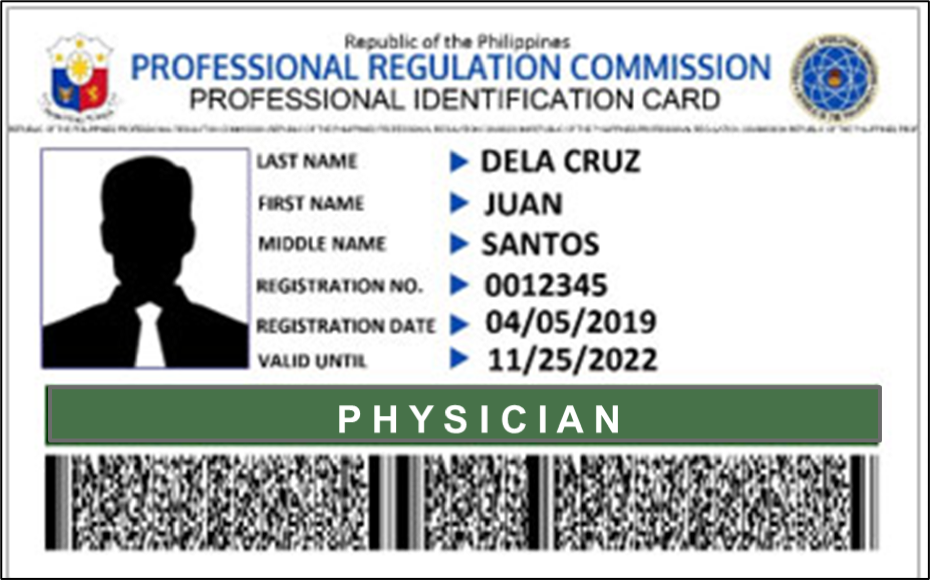
PRC ID
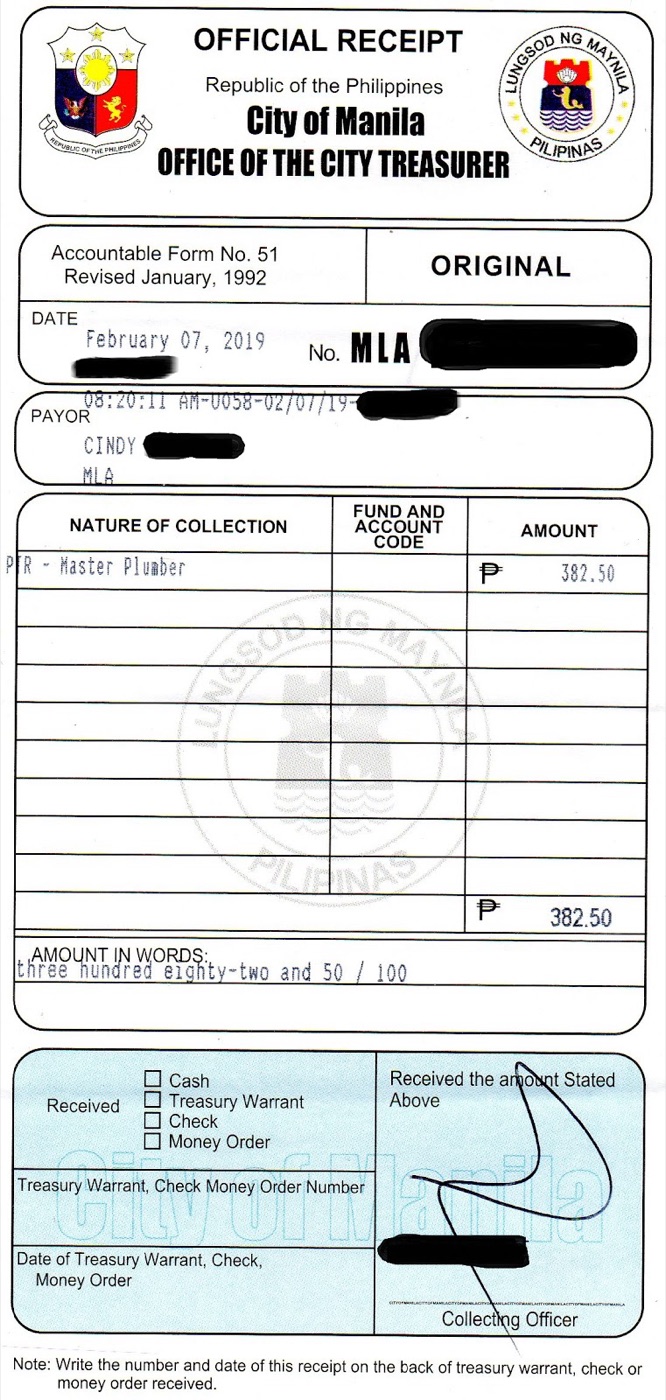
Professional
Tax Receipt (PTR)
Valid government issued
photo ID with address
Alternative: Brgy Certificate
- Philippine National ID
- Passport
- Driver’s License
- SSS UMID Card
- Voter’s ID
- Senior Citizen ID
- PWD ID
- Philhealth ID
- Postal ID
- GSIS eCard
Process
- COR
- Form 2303
- Cash Registry
- Cash Disbursements
- Patient Registry
- SC/PWD
- General Journal
- General Ledger
- Via ORUS (QR)
- Via RDO (Stamped)
- Via accredited printer
- Options:
- Permanent
- Temporary
- Php 1,500 mostly for 10 booklets
What’s Next?
TAX INDEX
| TAXES | |||
|---|---|---|---|
| Tax Type | Quarter | BIR Forms | Deadlines |
| Income Tax | 1st Quarter | 1701Q | May 15 |
| 2nd Quarter | 1701Q | August 15 | |
| 3rd Quarter | 1701Q | November 15 | |
| Annual | 1701A or 1701 | April 15 of the following year | |
| Percentage Tax | 1st Quarter | 2551Q | April 25 |
| 2nd Quarter | 2551Q | July 25 | |
| 3rd Quarter | 2551Q | October 25 | |
| 4th Quarter | 2551Q | January 25 of the following year | |
| Registration Fee (Discontinued) | Annual | 0605 | January 31 |
| PTR AND SWORN DECLARATION | ||
|---|---|---|
| Tax Type | Quarter | Deadlines |
| Professional Tax Receipt | Annual | January 31 |
| Sworn Declaration | Annual | January 15 |
TAX SCHEDULES: INCOME TAX, SWORN DECLARATION, PTR, ANNUAL REG FEE
15Sworn
declaration
31PTR
15Annual Income Tax
of Previous Year
151st Qtr
Income Tax
152nd Qtr
Income Tax
153rd Qtr
Income
Tax
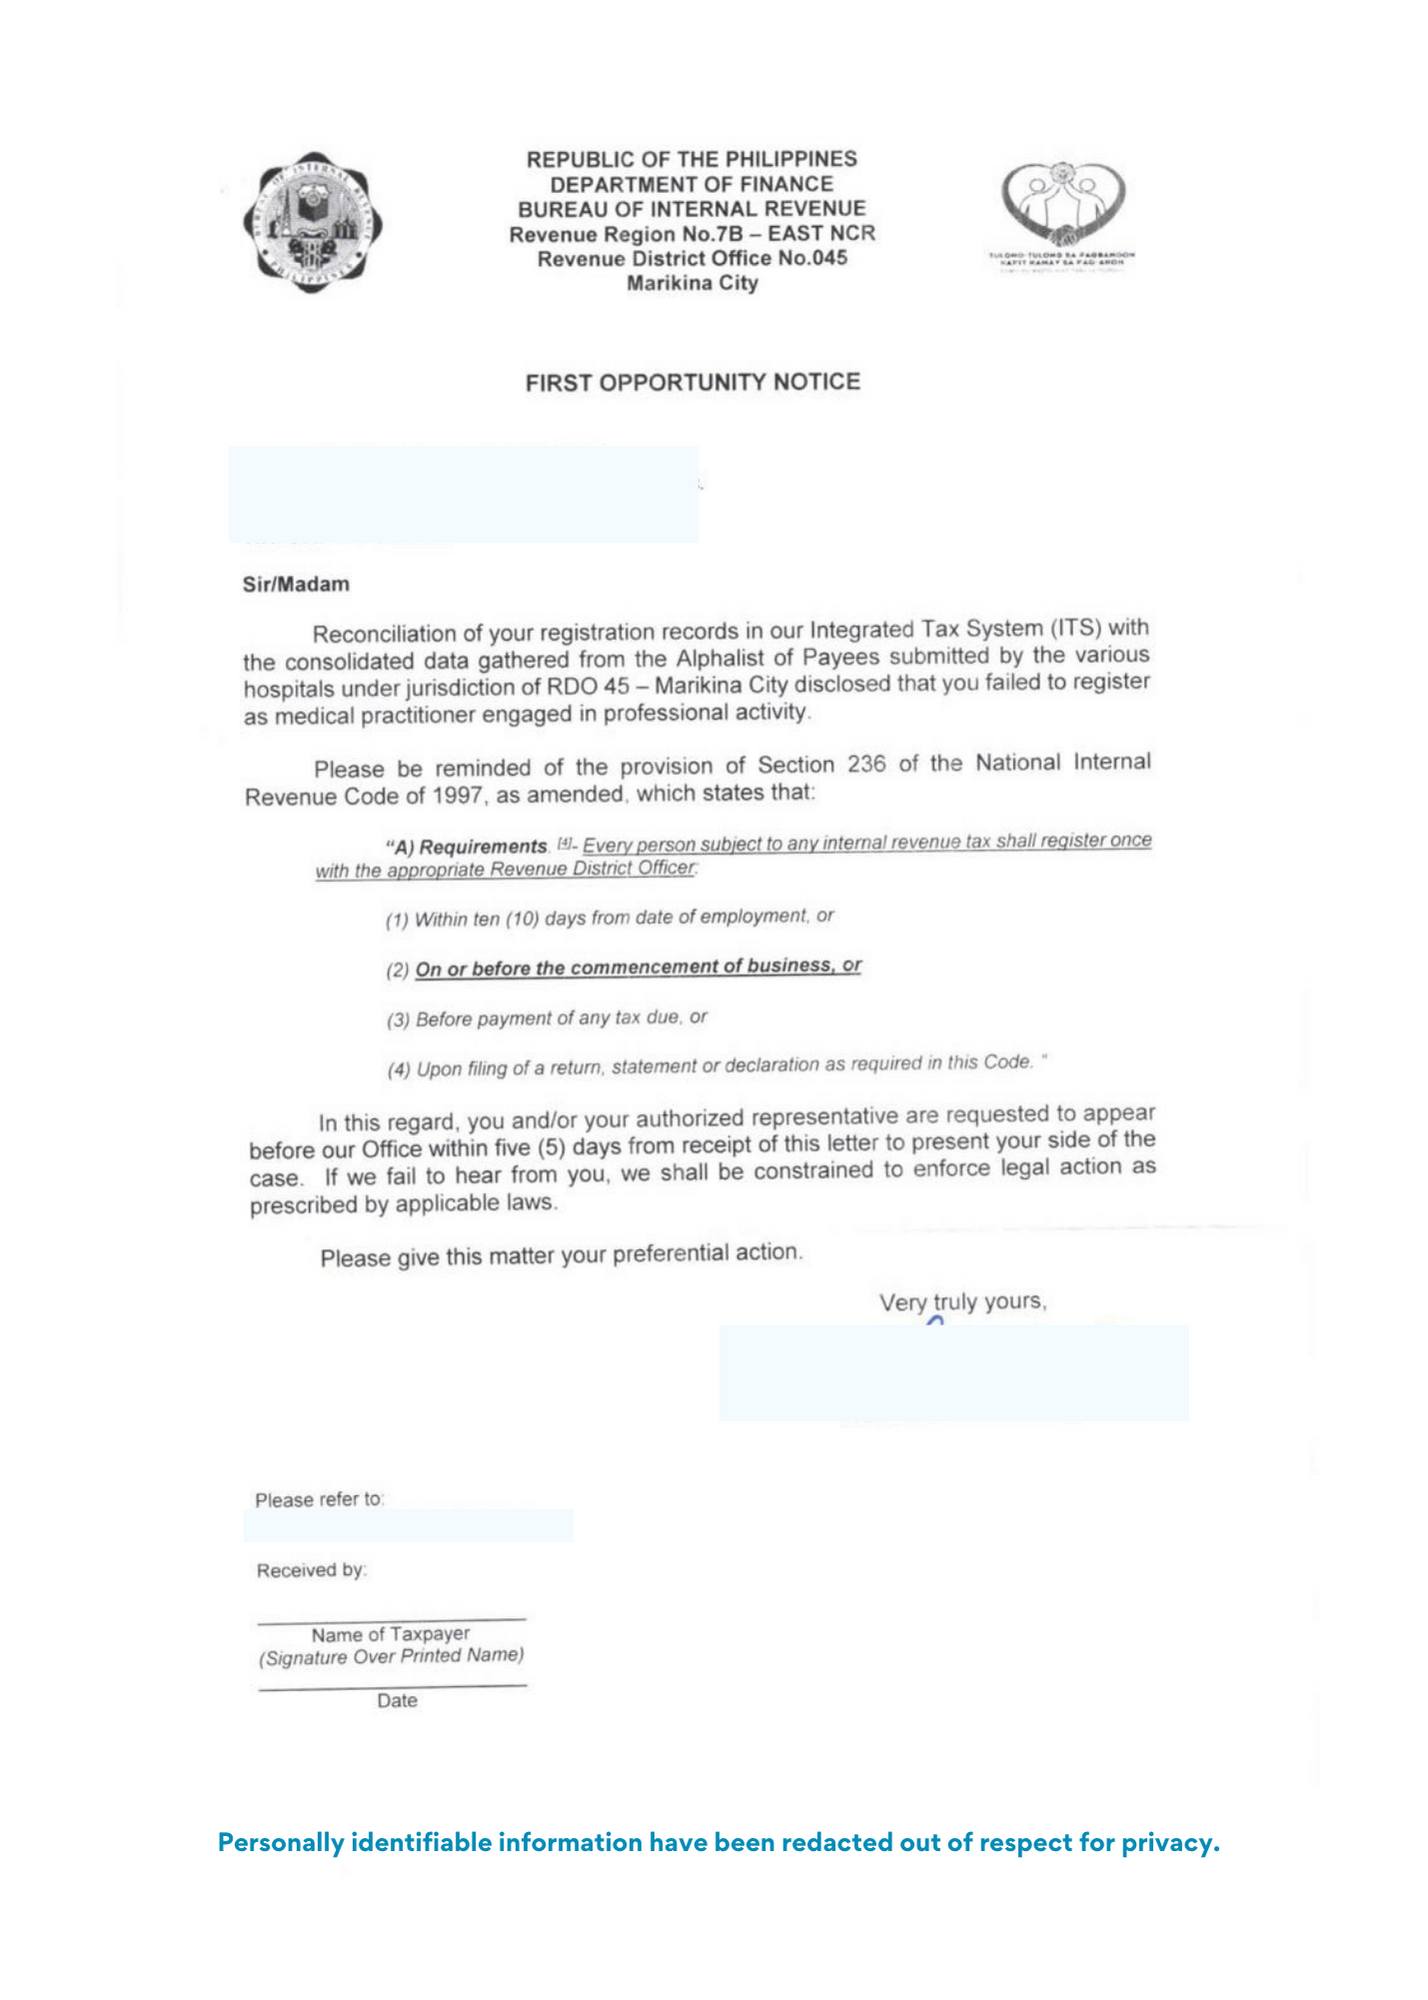
What if I opt not to Register?
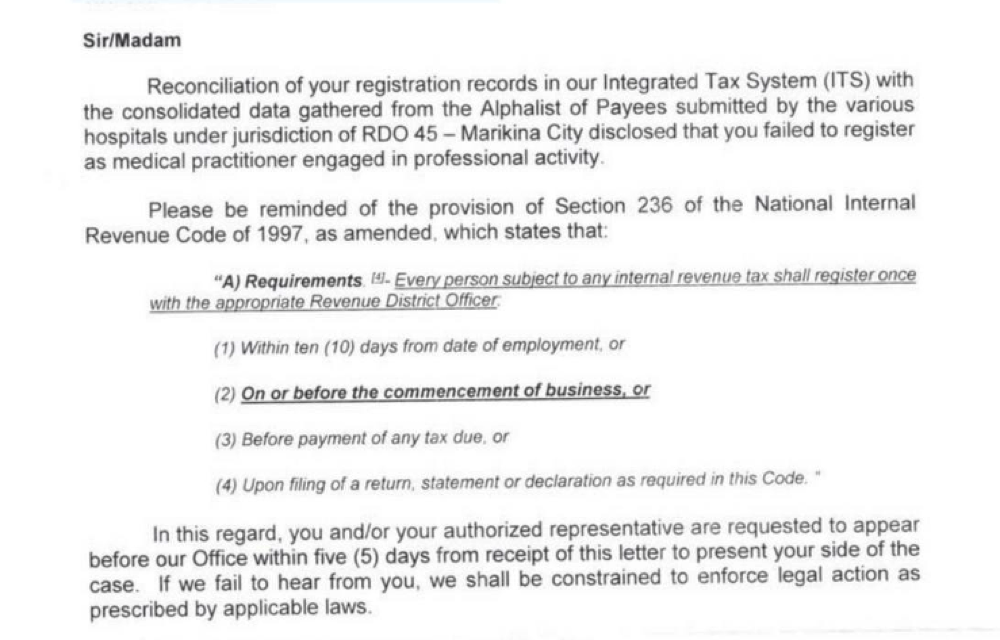
Key Information
Reporting your tax information through prescribed forms and channels.
Transfer of money from you to BIR.
Tax Payment
- Our obligation to the government
- Calculated every 3 months
- Income Tax collected in advance
- Compared against Income Tax
Withholding Tax:
How BIR keeps track of us
Withholding Tax
Institutions
2307
Return
- Collect proactively
- File as income tax
- Invoice must match 2307
- Invoice may be issued before Form 2307
EOPT: Service Invoice
before Payment
2307 and Service Invoice
Matching
=
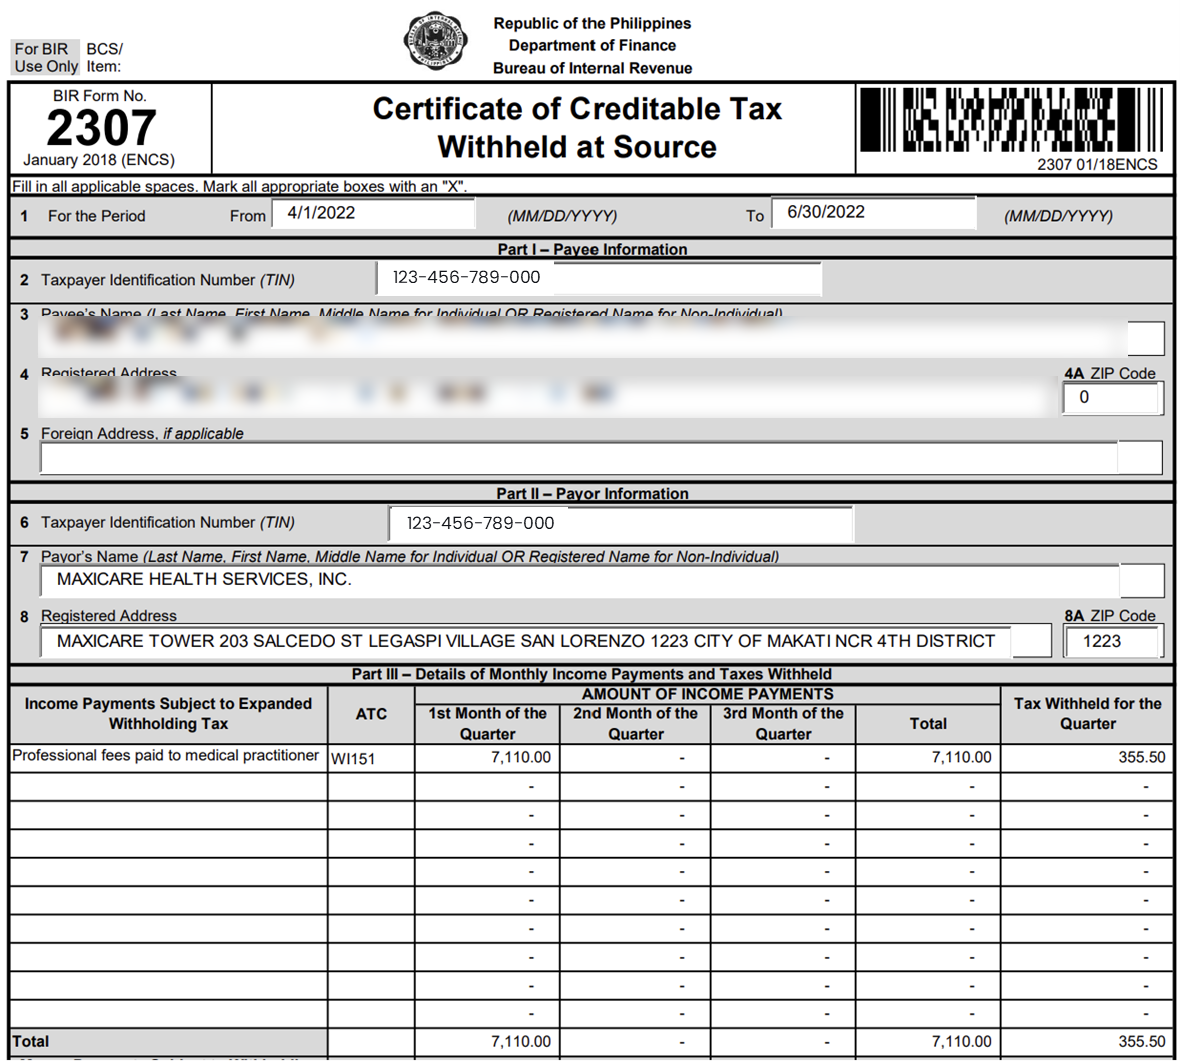
- Gross
- Net
- 6,754.50
- Withholding
- 355.50
receive
Engagement Types
| Element | |||
|---|---|---|---|
| Type of Engagement |
|
|
|
| Mandatory Benefits (SSS, PhilHealth, Pag‑IBIG) | You are responsible for filing your own benefits |
Deducted and filed by the employer, including employer contributions |
Elective |
| Paid Leaves | Usually none |
Sick Leave and Vacation Leave, as mandated by law |
As applicable to employers |
| BIR Registration | Required |
Not required |
Required |
| Tax Responsibility | Responsible for filing own taxes |
Employer is responsible for filing income tax |
|
| Issuance of Invoice or Receipt | Required |
Not required |
|
| Tax Forms Received from Payor | Form 2307 quarterly |
Form 2316 annually |
Form 2307 and Form 2316 |
| Work Status | Independent contractor |
Organizational employee |
Both |
| Income | Professional fees from patients and organizations |
Salary |
Both |
INCOME
Graduated ISD
- Tax Types: Income Tax & Percentage Tax
- (Gross − Allow. Ded.) x Grad Tax Table
- Allowable deduction = expenses
Graduated OSD
- Same as Graduated ISD
- Allowable deduction = 40% of Gross Inc.
Value Added Tax
- ≥ Php 3M in earnings
- Need to manage invoices
- Locked in 3 years
8% Flat Tax Rate
- No VAT or Percentage Tax
- First Php 250k is nontaxable
- Tax Rate: 8% after Php 250k
Graduated ISD
(Gross
Income−Itemized
Expenses)xGraduated
Tax Rate
3% of Gross Income
Graduated OSD
(Gross
Income−40% of Gross
Income)xGraduated
Tax Rate
3% of Gross Income
Value Added Tax
(Gross
Income−Itemized
Expenses)xTax Rate
Output
VAT−Input
VAT
8% Flat Tax Rate
(Gross
Income−250,000)x8%
Graduated Tax Table
| Net Taxable Income | Rate | |
|---|---|---|
| Over | But Not Over | |
| 0 | 250,000 | 0% |
| 250,000 | 400,000 | 15% of the excess over 250,000 |
| 400,000 | 800,000 | 22,500 + 20% of the excess over 400,000 |
| 800,000 | 2,000,000 | 102,500 + 25% of the excess over 800,000 |
| 2,000,000 | 8,000,000 | 402,500 + 30% of the excess over 2,000,000 |
| 8,000,000 | 2,202,500 + 35% of the excess over 8,000,000 | |
 Expense
VAT
Income Tax
( − Php 250,000 ) X 8% Income Tax
- First Php 250,000 is nontaxable
- 8% Income Tax Rate
- 10% default
- 5% for those with Sworn Declaration
Withholding Tax Rate
WT for those with no Sworn Declaration
Income Tax Rate
WT for those with Sworn Declaration
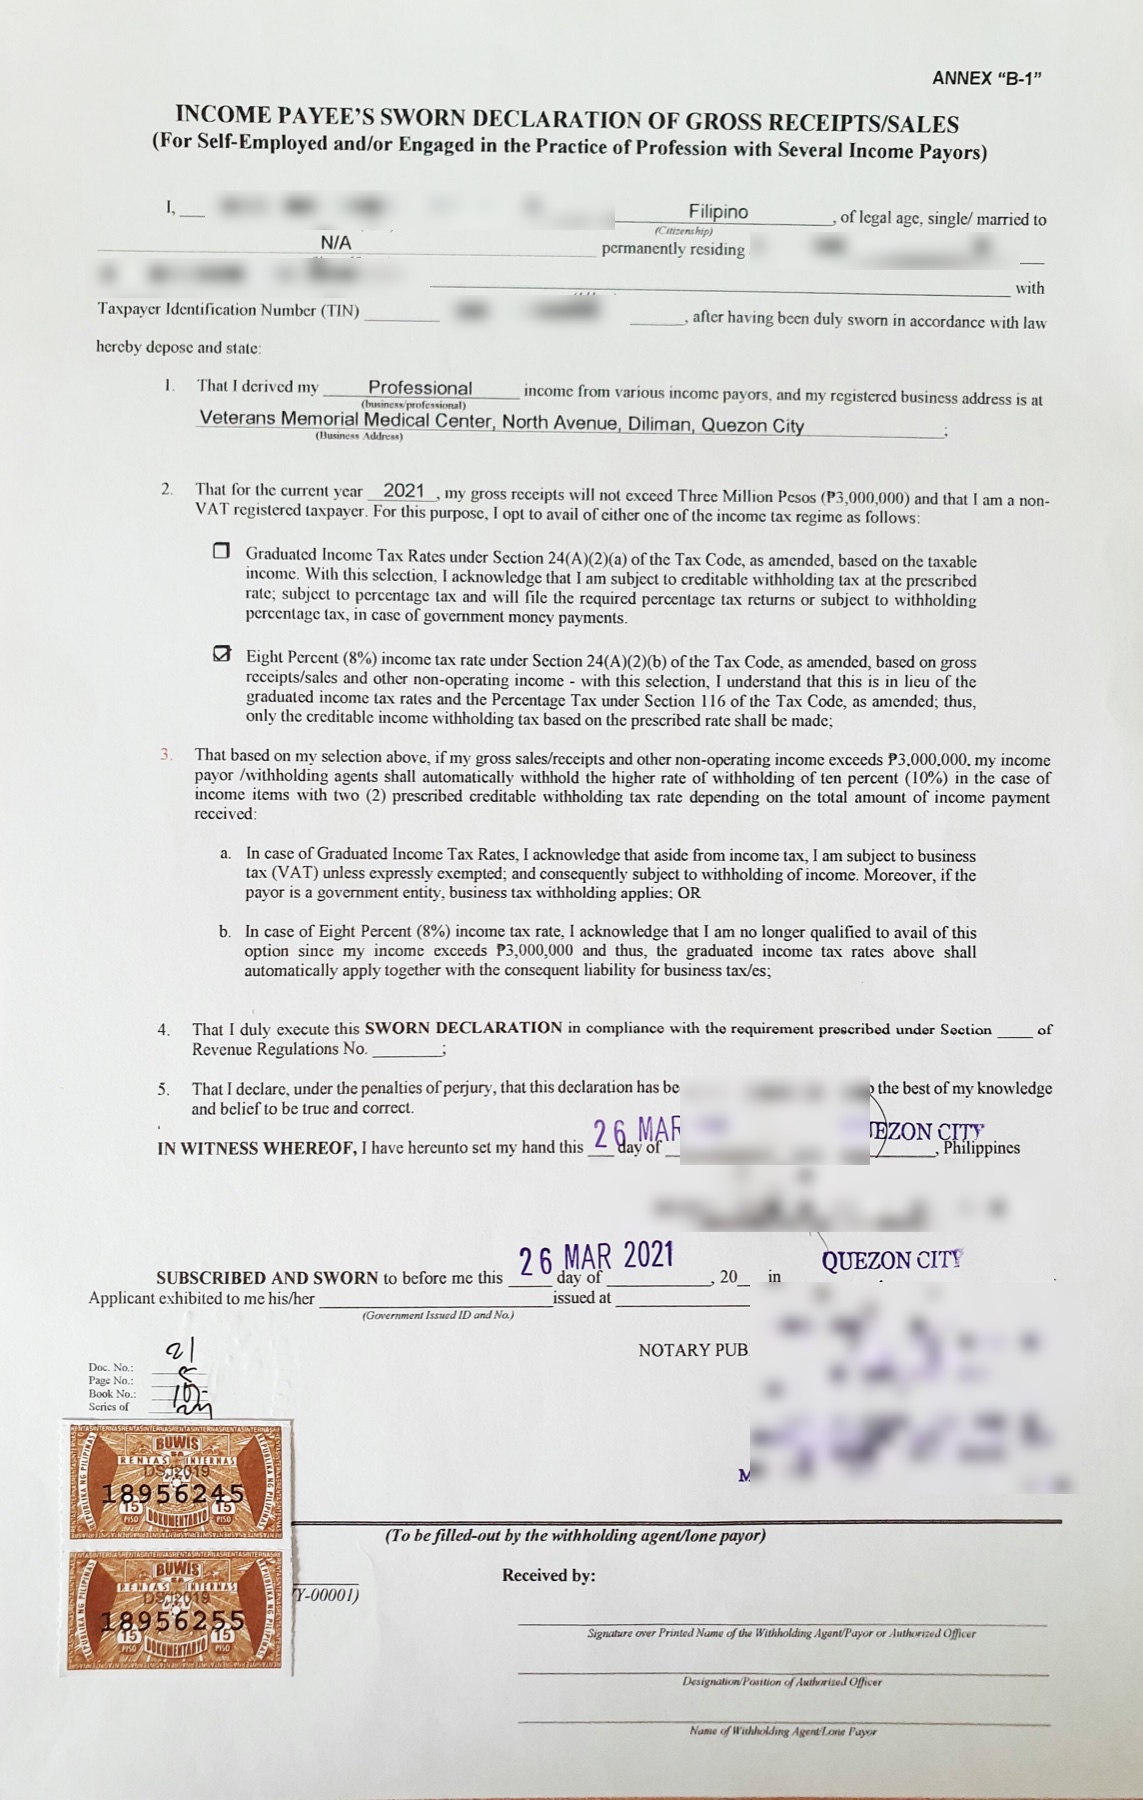
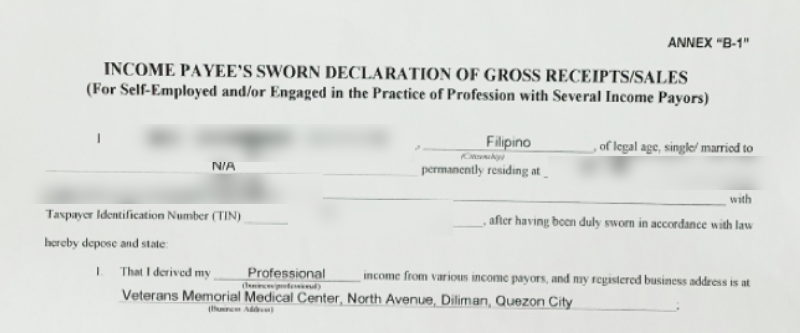
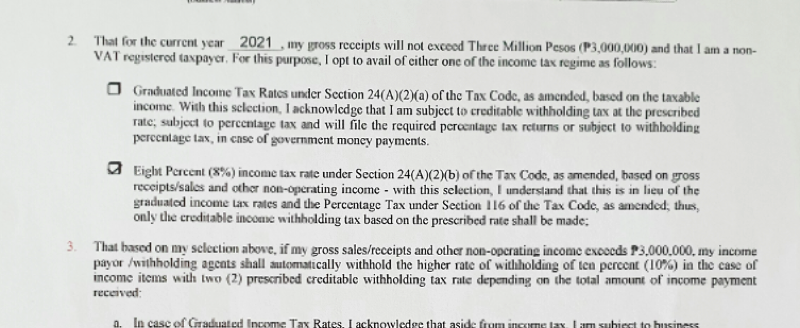
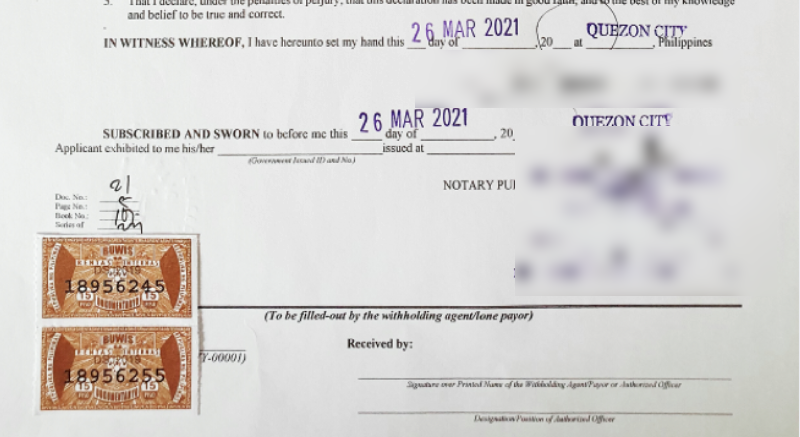
Sworn Declaration(RR 11-2018, p7)
Individual payees whose gross receipts/sales in a taxable year shall not exceed ₱3M, are required to submit a sworn declaration of his/her gross receipts/sales (Annex “B-1”), together with a copy of Certificate of Registration (COR), to all the income payor/withholding agents not later than January 15 of each year or at least prior to the initial payment of the professional fees/commissions/talent fees, etc in order for them to be subject to five percent (5%). The ten percent (10%) withholding tax rate shall be applied in the following cases: (1) the payee failed to provide the income payor/withholding agent of such declaration; or (2) the income payment exceeds ₱3M, despite receiving the sworn declaration from the income payee. In the case of individual payees with only one payor, the sworn declaration to be accomplished shall be Annex “B-2” and submitted, together with a copy of their COR, to the said lone income payor.
Key Info: Issuance Date
➤ Issued not later than January 15th or
➤ Prior to the initial payment of the professional fees
BIR
COMPLICATIONS
Complications
Lack of Expertise
Spreadsheet
Service
Provider
File
Management
Localization
RECOMMENDATIONS
Delivery Channel
2307 and Service Invoice
Matching
=
Consider the
Client Portfolio
Expertise
Client Focus
High Client Volume
Pro: Can mean higher level of expertise
Con: Overlooked taxes
Check for Digitization
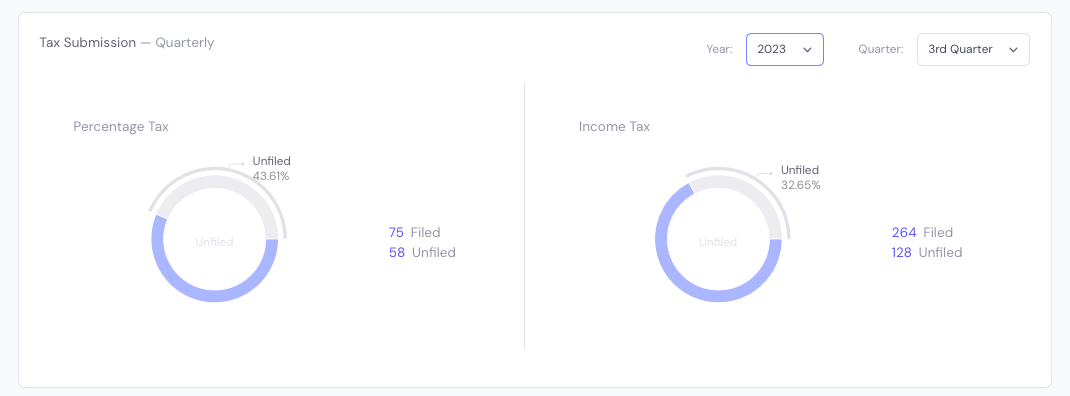
Are tax filing schedules tracked via Excel or is it tracked in an automated way?
Plot Tax Filing Schedules
 Certificate of
Registration
 Tax Calendar
Quarter 1Quarter 2Quarter 3Quarter 4
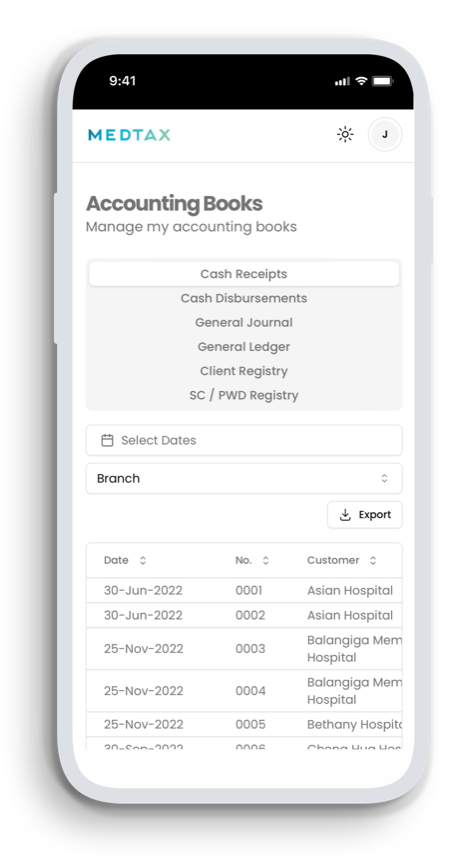
Those who plan to open clinics: consider Loose Leaf (digital accounting books)
Have backup copies.
Don’t wait for deadlines.
THANK YOU
FAQs
FAQs
 Facebookhttps://web.facebook.com/Medtaxph
 Websitewww.medtax.ph
 FAQs for TopnotchAvailable Tomorrow
Miscellaneous
HOW OUR SYSTEM WORKS
Form2307 Service
Invoice
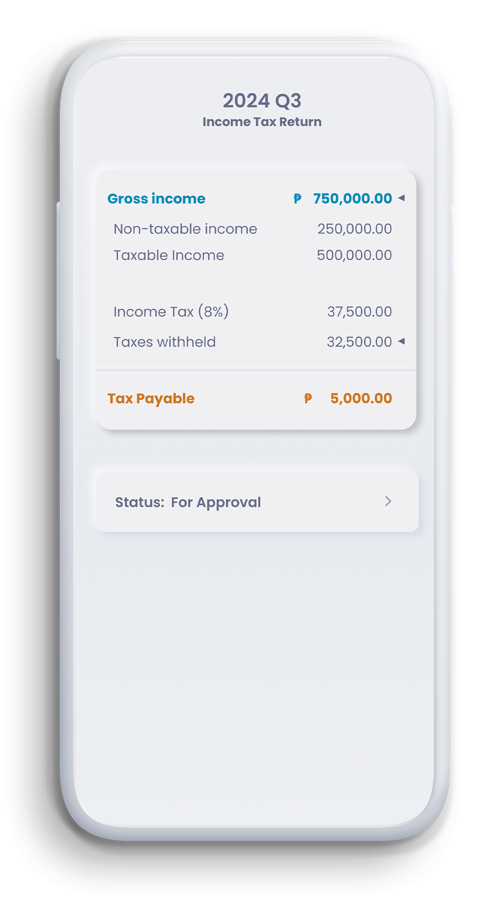
Proof of earnings such as Form 2307 and Service Invoices are uploaded onto the system
The system processes these data and utilizes them to generate the Tax Returns and Books of Accounts
PRICING
PRICING
- Php 11,596 total in a year
- Php 899 during Residency/Fellowship
- Save 20% or Php 2,396
- Php 3,050/yr during Res/Fellowship
- Php 8,000 for 3 years during Res/Fellowship
BIR REGISTRATION COSTS
| Item | Unit | Cost (Php) |
|---|---|---|
| Service Invoice | 10 booklets | 1,500.00 |
| Books | 1 set | 350.00 |
| Documentary Stamp Tax | 2 pcs | 60.00 |
| Special Power of Atty | 1 pc | 230.00 |
| Service Fee | 3,000.00 | |
| Total | 5,140.00 |
- Sworn Declaration: Php 230.00 for 1 copy; Php 305.00 for 3 copies, Php 410.00 for 6 copies
- Professional Tax Receipt: Php 300 plus Php 350 service fee
The above registration costs are for NCR and may change without prior notice. Costs in other areas may vary slightly.
FAQs
Quick FAQs
- Q: Do I have to register with the BIR as a medical professional?
- A: Yes.
- Q: Do I have to issue service invoice for my 2307, even if the hospital does not require it?
- A: Yes.
- Q: If I register with the BIR, will it hurt my cash flow?
- A: Generally, tax compliance can be good for cash flow.
- Q: If I am undergoing residency or fellowship, am I required to register with the BIR and file taxes?
- A: Generally, under government plantilla, no. But in a private hospital or if you’re under plantilla and have an existing COR, yes.
- Q: If I fail to comply with tax filing and BIR Registration, how will the government know about it?
- A: Withholding Taxes.
- Q: Do I have to collate my relative expense receipts to help manage and potentially lower taxes?
- A: New doctors, bad idea. Earning more than 3M, yes.
The answers are subject to further details which we’ll explore later.
Specific FAQs
- Q: How do I register and file taxes?
- A: We’ll cover this shortly
- Q: What to do when Tax Mapping happens?
- A: Comply with all instructions and at the very least, (1) Make sure your accounting books are always up to date, (2) You have Form 2307 for all earnings with withholding tax and they are properly filed, (3) Invoices have been issued to all transactions and (4) you have proper transaction trail such as having copies of all documents such as past income tax returns and even Form 2307
- Q: Difference between vatable and nonvatable
- A: Php 3,000,000.00 in gross earnings annually
- Q: How does EOPT affect doctors?
- A: (1) Those who have Official Receipts prior to EOPT should have converted them by now to Service Invoice and (2) Issue Service Invoice prior to payment. Note that you must now match Form 2307 and Service Invoice.
- Q: Lahat ba ng clinics (if multiple) need magapply for a separate receipt?
- A: If patients are paying you directly, yes. If patients are paying hospitals directly and hospitals are paying you, no.
The answers are subject to further details which we’ll explore later.
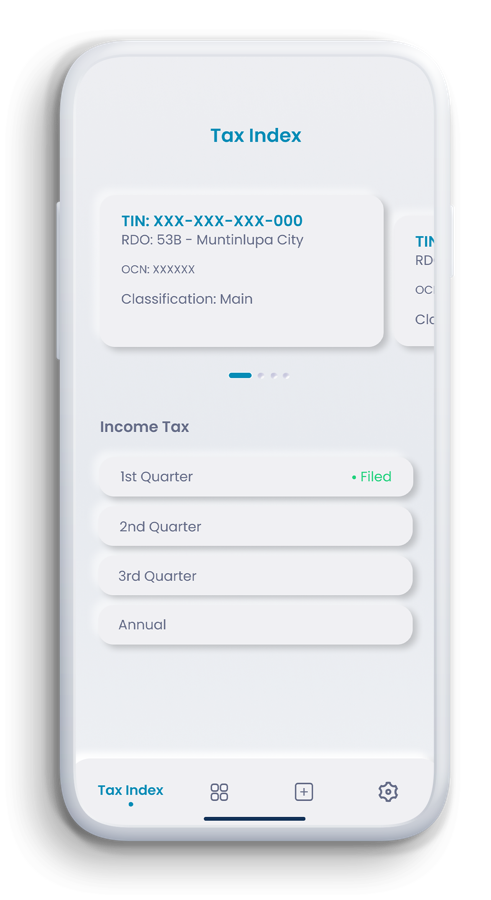
Tax Index
Complete list of taxes gives you a clear picture of your tax deadlines.
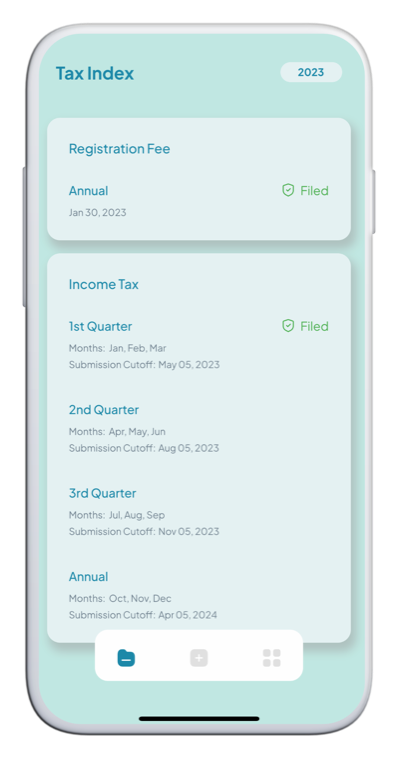
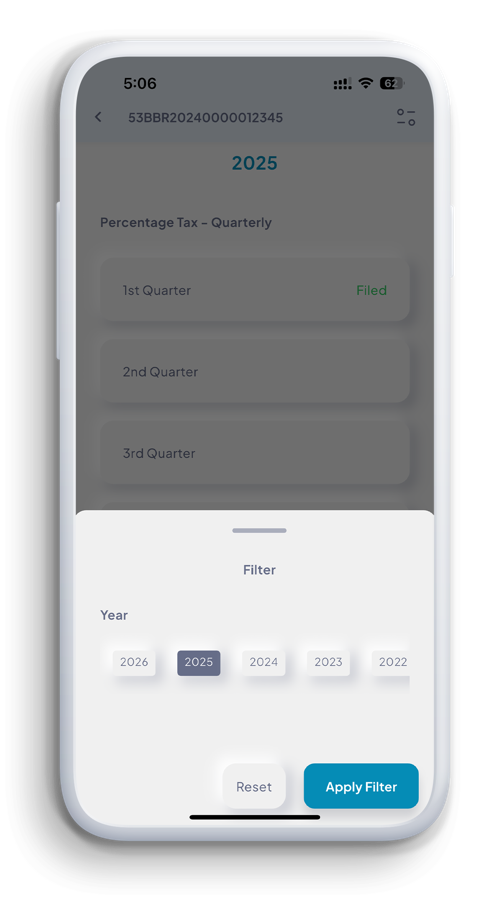
Access prior year’s tax returns.
Indicates the tax returns that have been filed for already. Clicking this section allows you to view and download your actual tax return.
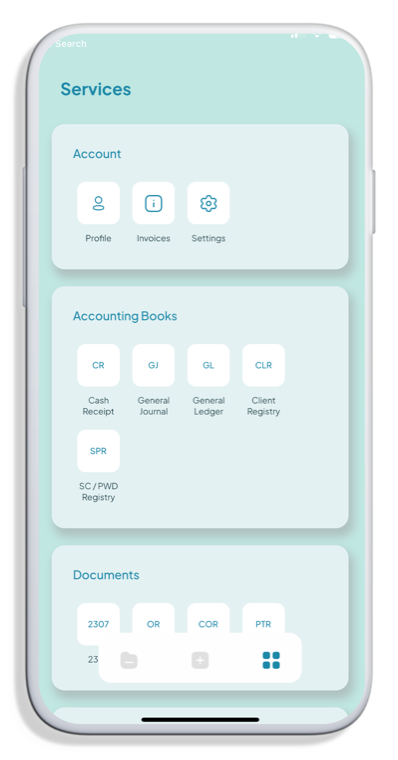
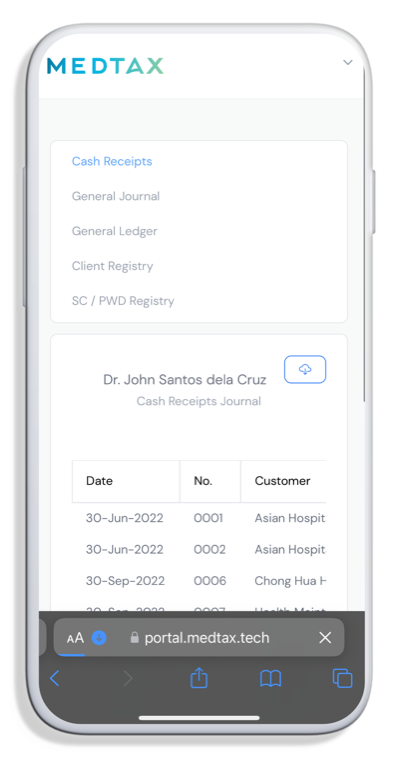
Digitized Books of Accounts
Access your Books of Accounts online. View, or download to Excel, so you can easily copy them onto your physical books.
Advanced Management of OR and 2307
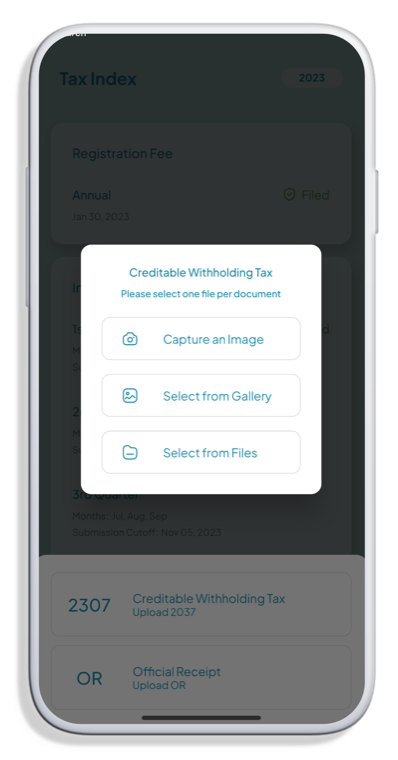
Upload your Form 2307 and Service Invoices. The system will process them into measurable data which reflect the details of your earnings.
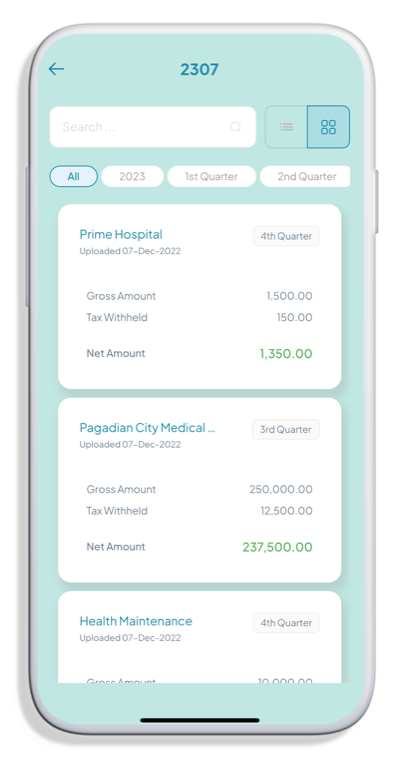
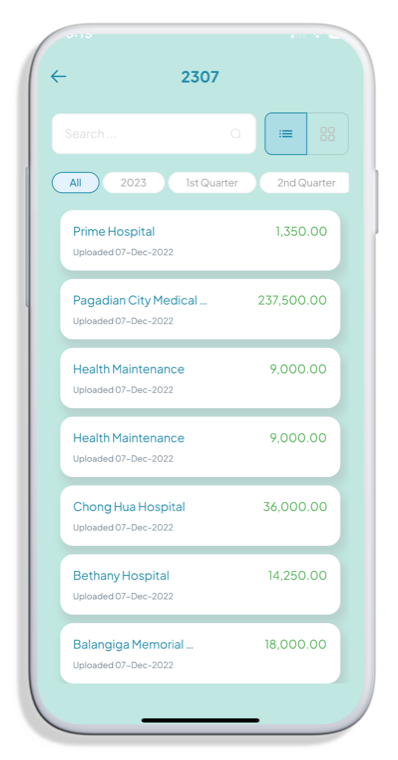
Automatically Generate OR Drafts
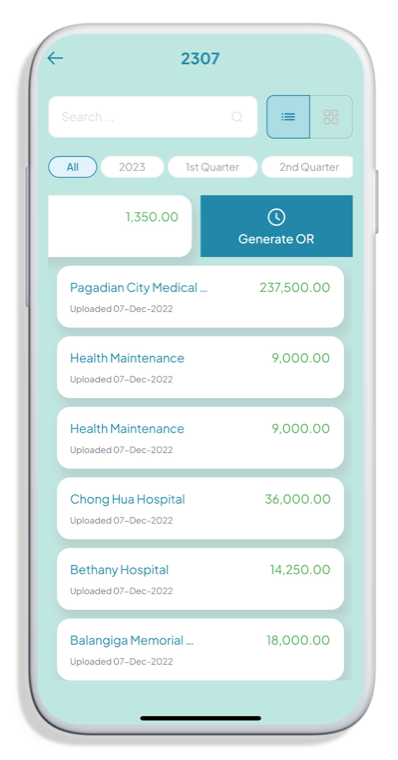
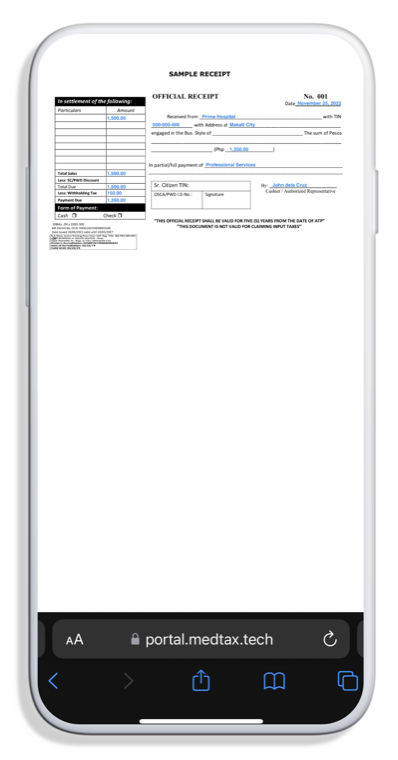
Generate drafts of the Service Invoice that you need to issue.
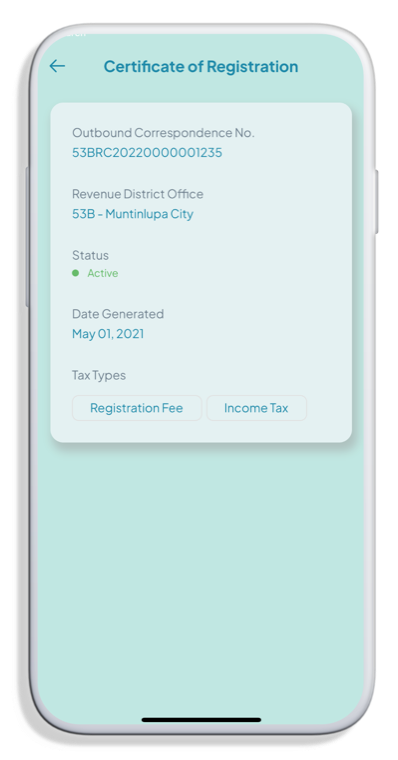
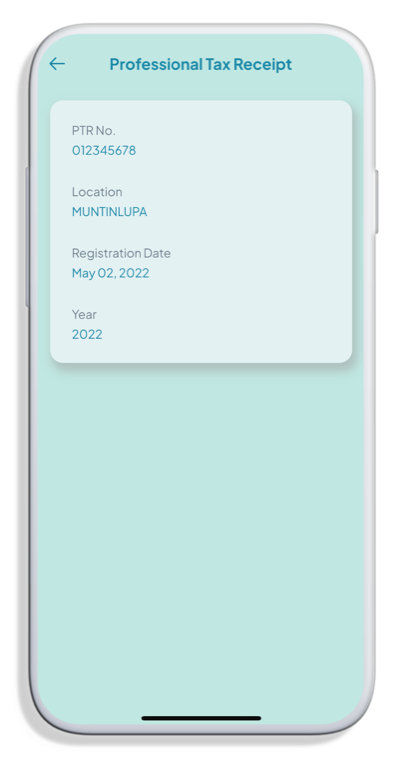
Track Other Documents
Keep track of your other documents such as PTR and COR. You can view them and download them as well.
How we Ensure Taxes are Filed
THANK YOU FOR YOUR TIME
- Q: Do I have to register with the BIR as a medical professional?
- A: Yes. The government and most hospitals require self employed professionals, including doctors in private practice, to register with the BIR.
- Q: Do I have to issue service invoice for my 2307, even if the hospital does not require it?
- A: Yes. BIR requires the issuance of a service invoice for every professional fee received, even if the hospital does not explicitly ask for it.
- Q: If I register with the BIR, will it hurt my cash flow?
- A: No. In fact, tax compliance is generally good for cash flow.
- Q: If I am undergoing residency or fellowship, am I required to register with the BIR and file taxes?
- A: If you are employed, under a government Plantilla, you may not register or file for closure if you have an existing COR. In all other cases, you’re generally required to file your taxes.
- Q: If I fail to comply with tax filing and BIR Registration, how will the government know about it?
- A: Earnings generally have withholding taxes. These are reported to the government.
- Q: Do I have to collate my relative expense receipts to help manage and potentially lower taxes?
- A: For new doctors earning less than Php 3M, this is for the most part not a very good idea. For those earning more than Php 3M annually, yes.
What else to expect: How your taxes are calculated, withholding tax details
© 2025 Medtax Solutions Inc. All rights reserved.